What Credit Score Do You Need to Buy a Home in North Texas?
Less than most people think. The long-standing benchmark for loans backed by Fannie Mae and Freddie Mac is a 620 score, and even that isn't a hard rule for every loan they back. Fannie Mae's research found that consumers consistently guess higher: as recently as 2023, the average guess was 652. Your lender sets the final requirement, and the scoring models behind your number are changing, so talk to a loan officer before you decide you can't qualify.
I hear a version of this from sellers all the time: "We'd love to move up, but I'm not sure where our credit stands." Strong income and a paid-down home don't guarantee a number you've actually looked at lately. Here's what I'd want you to know before you list your home and start shopping for the next one.
Most Buyers Are Guessing About Credit Scores
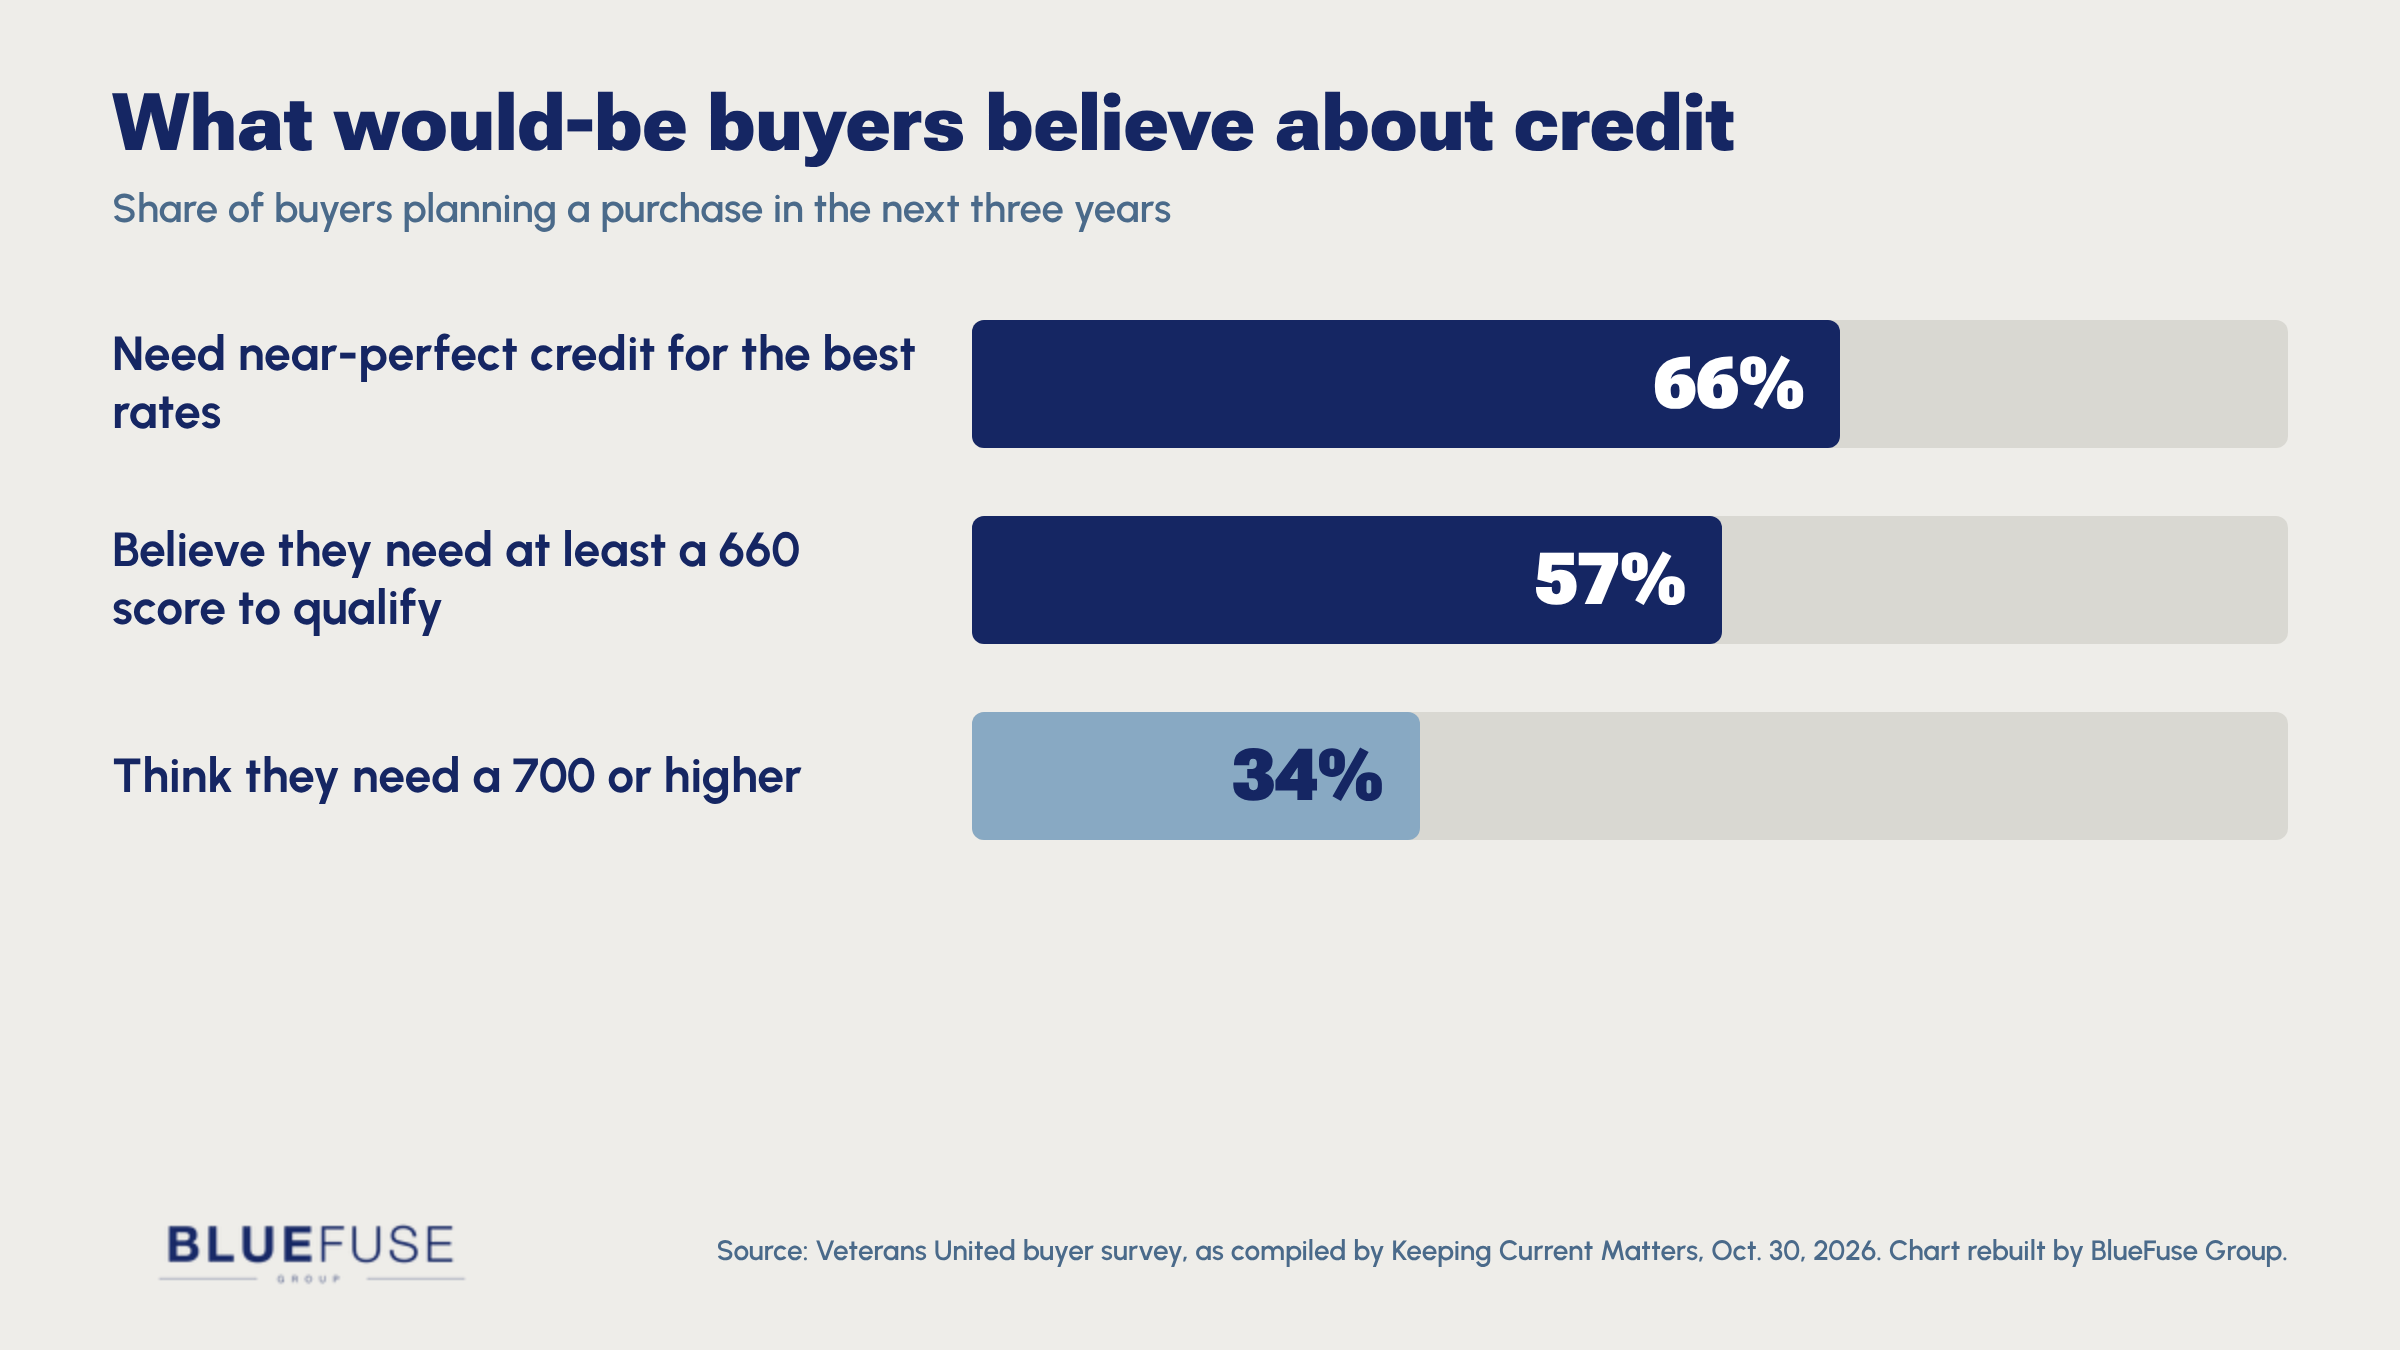
Fannie Mae has tracked consumer perceptions of mortgage requirements since 2015. The pattern holds year after year: people overestimate the minimum score lenders require. Veterans United surveyed buyers planning a purchase in the next three years and found the same thing.
Guessing wrong costs you. A renter who assumes their score is too low may never take the steps to find out for sure. And a homeowner who assumes their credit is fine may not check until the week they apply.
The Credit Score Models Behind Your Mortgage Are Changing
For decades, the mortgage industry relied on one set of scores: Classic FICO. The Federal Housing Finance Agency (FHFA) has since approved additional models, including FICO 10T and VantageScore 4.0, as part of a push for more competition and more inclusive scoring.
A different model can mean a different number for the same person. VantageScore says its model can score about 33 million adults that Classic FICO can't. So the score you saw on an app last month may not be the one your lender pulls.
Approval of a new model doesn't mean every lender switched on the same day. Ask your loan officer which score they will use for your file. The models may be new, but the basics haven't changed.
What This Means at North Texas Prices
The 620 benchmark applies to conforming loans, and the size of your loan matters here. The 2026 baseline conforming loan limit is $832,750, according to FHFA. Here's what a 20% down payment looks like on the median sale prices Redfin reported for the three months ending September 2026:
- Flower Mound: $642,694 median. Loan of about $514,155 after 20% down.
- Argyle: $792,598 median. Loan of about $634,078 after 20% down.
- Southlake: $1,424,322 median. Loan of about $1,139,458 after 20% down.
That's an illustration, not a quote, and your own price and down payment will differ. But it shows why one number doesn't fit every move. A Southlake purchase can land above the conforming limit, and lenders who write those larger loans set their own credit standards, so the 620 benchmark doesn't automatically apply. Ask early which standards your lender uses for the loan size you're considering.
If your move involves selling and buying at the same time, the lender conversation belongs before you list, not after you're under contract. I walk through the sequence in selling and buying in Flower Mound at the same time. For the pre-approval steps, see how to get pre-approved for a mortgage in Southlake or the Dallas-Fort Worth pre-approval guide.
Your Credit Checklist Before You Sell and Buy
The score model may change. The advice for improving your score doesn't. Financial awareness and consistency, plus a little willpower, go a long way.
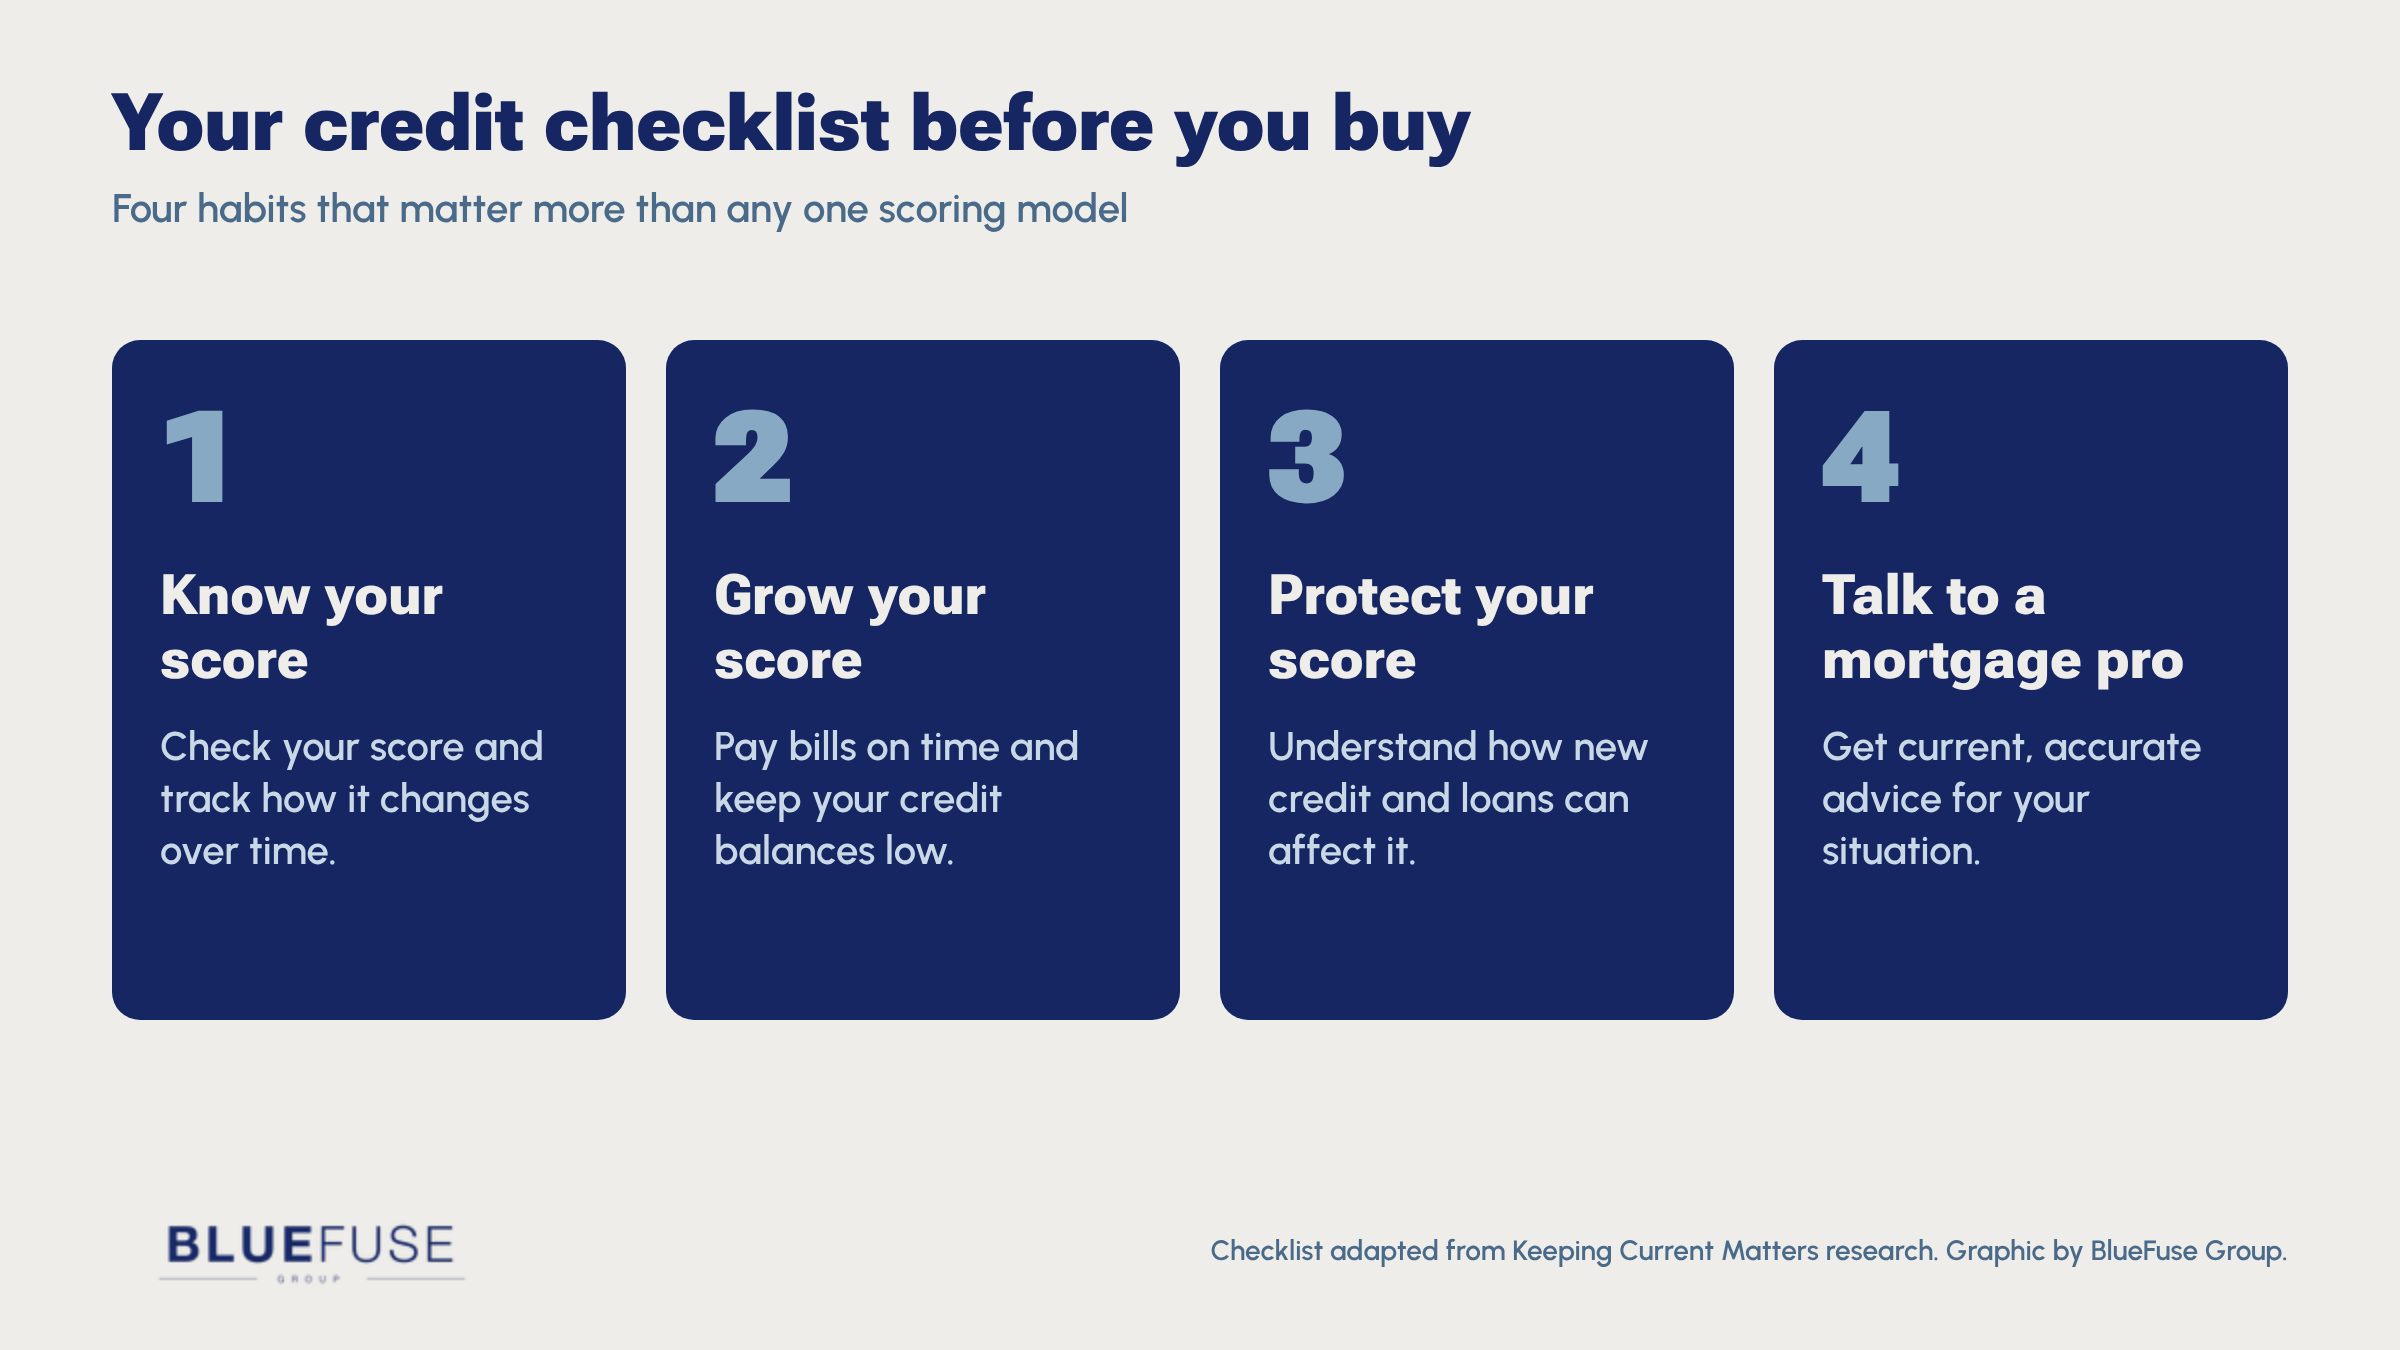
- Know your score. Check your score and keep track of how it changes over time.
- Grow your score. Pay your bills on time and try to keep your credit balances low.
- Protect your score. Understand how new credit and loans can affect it, and ask your lender before you open anything new while you're in the middle of a purchase.
- Talk to a mortgage pro. Get current, accurate advice for your specific situation.
Don't make credit or homebuying decisions from a chart, an app, or a friend's advice. With the rules shifting and so many misconceptions out there, it's never too early to talk with a professional loan officer about credit, budgeting, and what it would take to qualify. You may be closer to your next home than you think. If your down payment depends on your equity, my post on what you really need to know about down payments is a useful next read.
Frequently Asked Questions
What credit score do you need to buy a home in Texas?
The long-standing benchmark for loans backed by Fannie Mae and Freddie Mac is 620, and even that isn't a hard rule for every loan they back. Your lender sets the final requirement, and it can differ by loan type and loan size.
Do you need a 700 credit score to qualify for a mortgage?
No, 700 is not a universal cutoff. In the Veterans United survey, 34% of would-be buyers thought they needed a 700 or higher to qualify. A higher score can help your options, but assuming you don't qualify without checking is the costlier mistake.
Why is my credit score different from what my lender sees?
Different scoring models can produce different numbers for the same person. Mortgage lenders have relied on Classic FICO for decades, while apps often show other models. Ask your loan officer which score they will pull for your file.
Are FICO 10T and VantageScore 4.0 used for mortgages now?
FHFA has approved both models for use with Fannie Mae and Freddie Mac loans. That does not mean every lender has switched, so confirm with your loan officer which model applies to your application.
When should you check your credit before selling and buying?
Before you list your home. Knowing your score and talking with a loan officer early gives you time to fix surprises, and it lets you plan the sale and purchase together instead of reacting mid-contract.
Know Your Number Before You Make Your Move
Your credit score is one piece of your next purchase, and it's one you can check today. Know your score, ask which model your lender uses, and have the loan conversation before you list.
If you're thinking through a move like this, schedule a free Move-Up Strategy Call ... thirty minutes, no pitch, just a clear-headed look at where you are and what your best next move looks like.
This article is general information, not legal, tax, insurance, or lending advice. Verify your specific numbers with your agent, your lender, your title company, and where appropriate a licensed Texas attorney.
Sources: Fannie Mae consumer perception research, Veterans United buyer survey, and VantageScore adult-scoring figure, as compiled by Keeping Current Matters (October 30, 2026); Federal Housing Finance Agency (credit score model approvals and 2026 conforming loan limit); Redfin housing market pages for Flower Mound, Argyle, and Southlake (three months ending September 2026).
About Brian White
Brian White helps families in Northwest DFW make their move-up cleanly, selling and buying in one synchronized step. He built BlueFuse Group on a simple standard: other-first service, proactive at every turn, faith and excellence in equal measure. Brian has been married to Tisha for 27 years and is dad to three adult sons. When he's not protecting a family's equity or untangling a tight closing timeline, you'll find him chasing a round of golf or at Valley Creek Church.
Schedule a Move-Up Strategy Call ... no pitch, just a clear-headed look at your next move.